
(2026) Health Insurance in Dubai for French Expats: Complete Guide
Moving to Dubai from France? Our 2026 guide explains the healthcare system, medical costs, the CFE and how to choose the best insurance. Get a free quote.
Reviewed by a licensed advisor
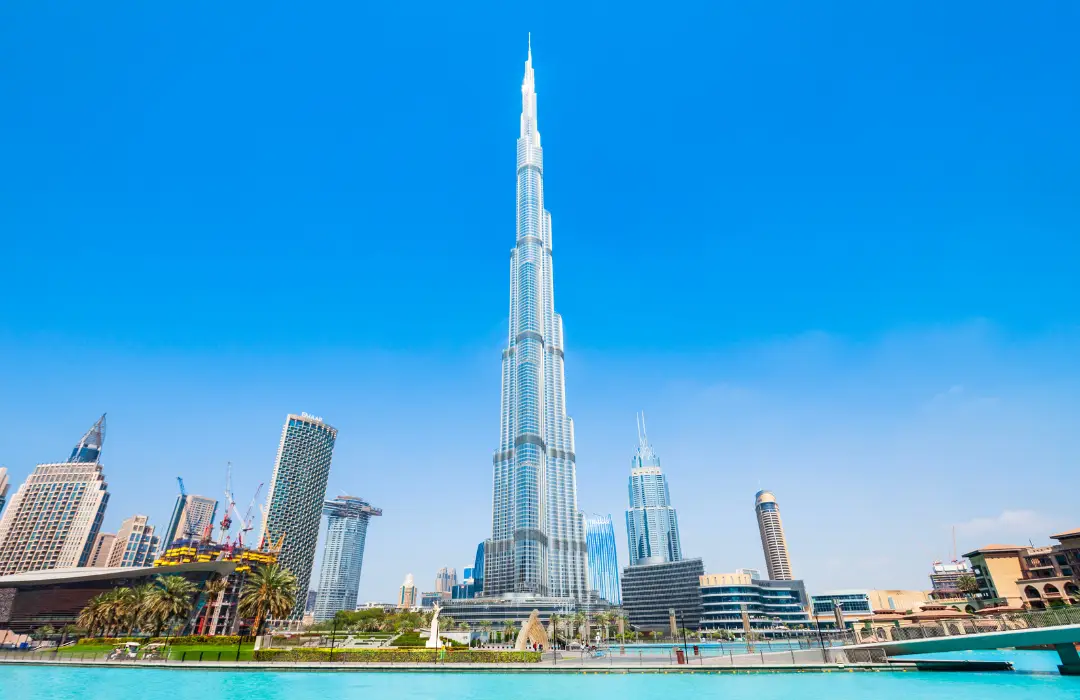
Dubai attracts many French expats with its job opportunities, modern lifestyle and attractive tax environment. However, its healthcare system needs careful preparation. Public services are mainly for nationals, and the private sector is highly developed and expensive. Without suitable cover, medical bills can be a major financial risk, especially as insurance is mandatory for residents.
The experts at Alea explain everything a French expat needs to know to stay well protected in Dubai.
Why you need health insurance in Dubai
High medical costs for non-residents
Healthcare in Dubai relies on high-end private providers, with prices much higher than in many European countries, especially for patients without insurance. Expats do not have access to the subsidies reserved for nationals, so they have to use the private sector, where providers set their own fees.
Examples of costs in Dubai:
GP consultation: about 200 to 500 AED (≈ 50 to 125 EUR) in a private clinic
Hospital stay in a private room: prices vary widely, and a stay can quickly cost several thousand AED per night
Common surgery (e.g. appendicitis): from about 10,000 to more than 30,000 AED depending on the hospital and the complexity, not including pre- and post-operative tests
Legal requirements linked to your visa
In Dubai, you can only get or renew a residence permit if you hold health insurance that complies with the local health insurance law (Dubai Health Insurance Law). Employers must provide minimum cover for their employees. Self-employed people, freelancers, long-term visitors and some visa holders (such as Golden Visa holders) must buy private insurance themselves to stay compliant.
Company cover is often limited
Group plans offered by employers often stick to the legal minimum (Essential/Basic Benefits Plan), with an annual limit of around 150,000 AED, high co-payments and a limited network. These plans do not meet the needs of an expat family well (maternity, specialist care, chronic conditions treated in private hospitals), and they end as soon as your employment contract ends.
Peace of mind and access to the best care
Good international insurance gives you direct access to networks of private hospitals and clinics, often with direct billing. You do not have to pay upfront or deal with complicated reimbursement claims at a stressful time.
Why you should not rely only on your employer's health cover
Read the terms and conditions of your group health plan carefully. You may find that it does not give you enough cover, or that you cannot keep your cover if you leave the company.
Insufficient cover
Even if your employer offers medical insurance, the cover may not be enough if you become seriously ill.
Most group health plans have limits, such as annual coverage caps, exclusions for certain treatments or restrictions on access to private healthcare facilities. This means that if you need extensive medical treatment or specialist care, you could face high costs. In these cases, a top-up plan can give you more complete cover, so you can get the medical care you need without financial strain.
Lack of portability
Very few expats realise that leaving or losing their job while living abroad can have serious consequences for their health cover. In the vast majority of cases, employer health plans are not portable. The few portable plans that exist come with strict conditions.
Why choose international health insurance rather than travel insurance?
Both types of insurance are designed for people who spend time abroad, but each product has a different purpose.
Make sure you understand the differences. Otherwise, your cover abroad may not be suitable and you could face unexpected costs.
Travel insurance
Travel insurance covers emergency treatment while you are in another country for a short period, so that you can return home once you have recovered enough. It rarely covers long-term medical treatment. If you need further care, you will have to go back to your home country. Travel insurance ends as soon as you return to your country of residence.
International health insurance
International health insurance is designed for people who live or work abroad for a long period. It covers both emergency and routine care. It gives expats a choice of doctor and healthcare facility, and the flexibility to get treatment anywhere in their area of cover.
With international health insurance, you can use private healthcare facilities whenever you need to. This way, you avoid long waiting times in the public sector.
The Caisse des Français de l’Étranger (CFE): a solution for French nationals living in Dubai
French nationals living in Dubai can join the Caisse des Français de l'Étranger (CFE), a social security fund designed specifically for French people living abroad. The CFE gives you health cover similar to the main French social security scheme, while leaving you free to choose your healthcare providers in Dubai.
Why choose the CFE?
Continuous social protection: the CFE lets you keep your French social security rights, so there is no gap in your cover if you return to France.
No health questionnaire: pre-existing conditions are covered automatically.
No waiting period if you move back to France.
Works alongside private insurance: the CFE alone is not enough, so we recommend a top-up plan to be well covered in Dubai and in the rest of the world.
As a CFE partner, Alea helps the French community choose and sign up for the right CFE option and the best top-up plan, so you get the protection that best fits your needs.
5 things to consider to find the best health insurance plan
Here is what to think about when you look for health insurance in Dubai:
Coverage
Check that the plan covers the usual costs in Dubai (specialist fees, medicines, private hospital stays). Options such as maternity or preventive care cover are a plus.
Customer service
When you look for an insurance provider, find out about their customer service. Do they offer 24/7 support? Can you reach them by live chat or by phone? Do they offer services in French?
This may seem minor at first, but whether you have a medical emergency or a question about your insurance claims, you need to be able to reach your broker or insurer for help.
Direct billing
Does your insurance offer direct billing? With direct billing, the insurer can pay the hospital, clinic or doctor directly, so you do not have to pay out of pocket and then file a reimbursement claim.
This makes it an excellent option for French people living abroad who find themselves needing medical care.
Claims handling
When it comes to reimbursement claims, some insurers have a strict policy of paying you quickly, while others can take several months. An efficient claims process saves you time and reduces stress.
Expertise
An insurance broker's role is to help you find the best plan for you and/or your family, suited to your needs and your budget.
A health insurance broker will help you:
Review and compare all the relevant health insurance plans, including top-up plans
Understand clearly how the market works and which options are best for you, with professional answers to all your questions
See how deductibles affect your overall healthcare costs
Handle complex situations if you run into unexpected problems with your claims
Defend your interests whenever you need it
Written by
François Bossé
Insurance Advisor


Need some help?
We’re here to provide support and assistance.
